VW Loan With a Co-Signer in Salt Lake Valley: Myths vs Facts
A co-signer can help your Volkswagen financing in the Salt Lake Valley — but not the way most buyers think. Here's what actually changes at approval.
A co-signer on a Volkswagen loan does not guarantee approval, does not lock in a specific interest rate, and does not give the co-signer any ownership of the vehicle. What it actually does is let the lender evaluate a second person's credit and income alongside yours, which can improve approval odds and loan terms — particularly for thin-file or lower-score buyers in the Salt Lake Valley — while making both of you fully, legally responsible for every payment.
That's the honest answer. The rest of this guide dismantles the specific myths Salt Lake Valley buyers bring to the finance desk, and explains the mechanism behind each correction.
Myth 1: "A co-signer guarantees I'll get approved for a VW loan in Utah"
False. A co-signer improves your odds but does not guarantee approval. Lenders still evaluate the full application — both parties' credit, income, debts, and the vehicle itself. If the co-signer has a high credit score and good credit history, lenders are far more likely to trust the primary borrower, but "more likely" is not "certain."
The mechanism: a co-signer reduces the lender's risk because a second person has legally agreed to pay if you can't. That reduced risk is what tends to produce both better approval odds and a better interest rate — not a rubber stamp. Volkswagen Credit does not publish a universal minimum credit score or a formula showing exactly how much a co-applicant changes the decision, so no one at a dealership — including Strong Volkswagen — can promise you a specific outcome before the application is submitted.
Myth 2: "A co-signer and a co-borrower are the same thing"
They are not. In a joint auto loan, two borrowers are equally responsible for paying back the loan. A co-signer, by contrast, acts as a backup — only expected to pay if the primary borrower cannot — and co-signers do not usually retain ownership of the vehicle.
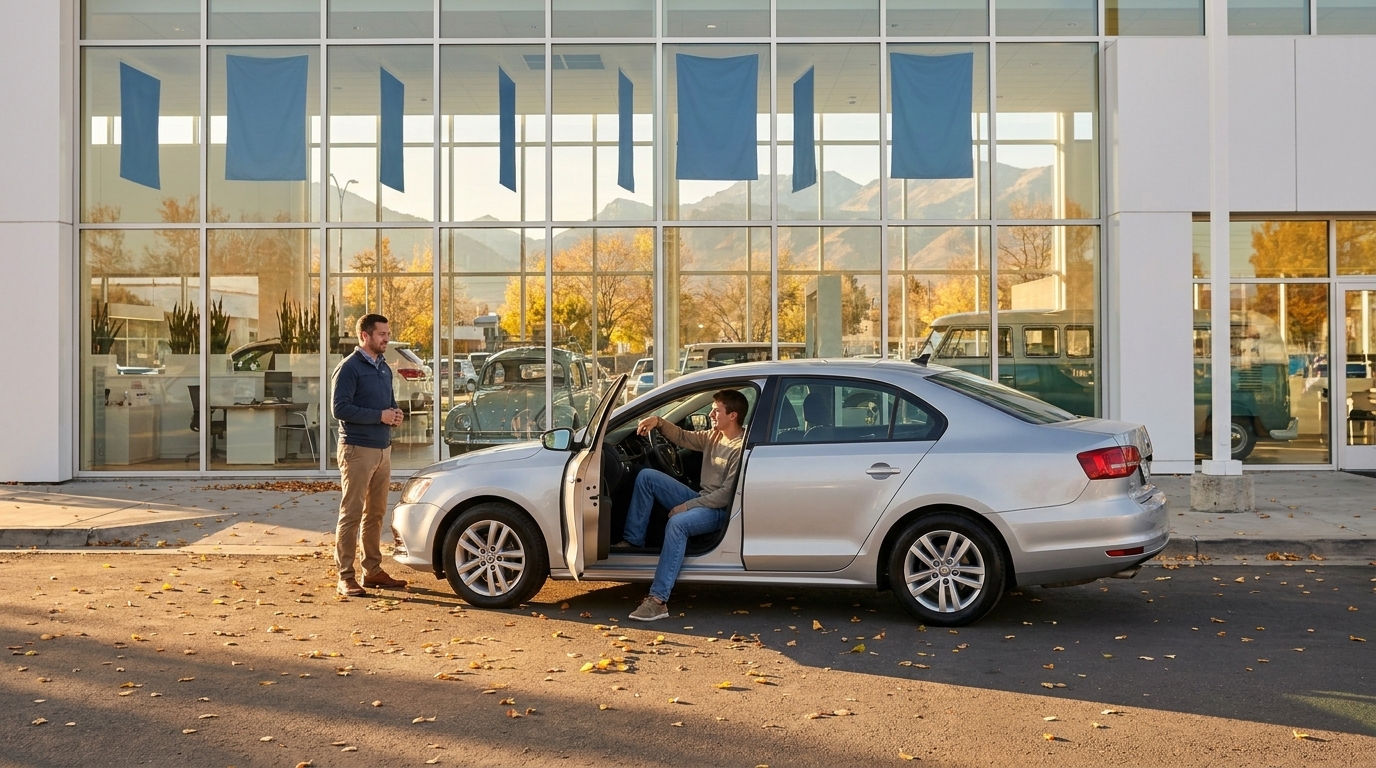
This matters at the Salt Lake Valley finance desk because the paperwork, title, and expectations differ. A co-signer agrees to back the loan without having a claim to the car; the primary borrower still owns the vehicle and makes the payments. If you're a parent helping a first-time buyer get into a 2026 Volkswagen Jetta, starting at $23,995 (as of October 2026) or a recent graduate stretching toward the 2026 Volkswagen Taos, starting at $26,500 (as of October 2026), understand which role you're actually signing into before you sit down.
Myth 3: "The co-signer just signs — they don't need to show up or submit documents"
Wrong, and this one derails more Salt Lake Valley deals than any other. Volkswagen requires both applicants to be physically present to complete a joint finance application, either at the dealership or online. Both parties also must supply the same documentation categories, not just the primary borrower.
Per Volkswagen's finance guidance, both applicants must provide: SSN or ITIN, valid ID, current proof of income, proof of residence, contact and employment details, monthly housing payment, and — if applicable — trade-in details. Cosigners also must meet minimum income requirements to prove they can handle the loan in case the primary borrower defaults. If your co-signer lives out of state, plan the online option in advance; showing up to Strong Volkswagen's showroom at 1070 South Main Street in Salt Lake City with only half the paperwork means driving home without the car.
Myth 4: "Co-signing is low-risk if the borrower is reliable"
No. A single missed payment can damage each person's credit score — both the primary borrower's and the co-signer's. The CFPB's co-signing guidance is blunt: co-signers can be responsible for the debt, late fees, and collection costs, and missed payments can affect their credit.
Co-signing for a loan means it is included in your credit history and incorporated into your debt-to-income ratio. That means a parent co-signing on a 2026 Volkswagen Tiguan, starting at $30,805 (as of October 2026) may find their own ability to qualify for a mortgage refinance temporarily reduced — not because they did anything wrong, but because the lender now sees that auto loan as partly theirs. Credit scores range across a broad spectrum; a score in the upper ranges is generally considered good, while scores in the lower ranges are viewed as poor, and a late payment can swing a co-signer's score materially in either direction.
Myth 5: "The co-signer owns part of the car"
They don't. A cosigner does not have partial ownership of the vehicle being purchased with the loan. The primary borrower still owns the car outright — the co-signer carries the risk without the keys, the title, or the equity.
This is a frequent source of family conflict down the road. If the primary borrower sells the Volkswagen, trades it in, or wrecks it, the co-signer has no legal claim to the proceeds, only to the remaining debt if payments stop. Buyers who want shared ownership should ask about a joint loan structure instead — a different product with different paperwork.
Myth 6: "Having a co-signer means I'm not building my own credit"
Backwards. The primary borrower still builds credit by making on-time payments even when a co-signer is on the loan, because the primary borrower is the one making the car payments. That's actually one of the most useful features of the arrangement for first-time buyers in the area.
A thin-file buyer in Salt Lake County can use a well-structured co-signed loan to establish a payment history over time, then refinance in their own name once their credit score supports it. The co-signer stays on the hook only until the loan is paid off or refinanced — not forever.
Co-signer vs. joint borrower at a glance
| Factor | Co-Signer | Joint Borrower |
|---|---|---|
| Legal responsibility for debt | Full, as backup | Full, equal |
| Expected to make payments | Only if primary defaults | Yes, equal payments |
| Ownership of vehicle | None | Shared |
| Appears on credit report | Yes | Yes |
| Affects debt-to-income ratio | Yes | Yes |
| Must submit full documentation | Yes | Yes |
How this plays out at a Salt Lake Valley dealership
Strong Volkswagen is a family-run business and the longest-running Volkswagen dealership in Utah, and the finance process for co-signed applications follows Volkswagen Credit's standard requirements — both signers present (in person or online), both document packets complete, both credit profiles pulled. The dealership also offers Spanish-language service on its website for applicants more comfortable reviewing finance terms in Spanish.
Shoppers weighing a lower-down-payment path on a 2026 Volkswagen Jetta, starting at $23,995 (as of October 2026) or the 2026 Volkswagen Taos, starting at $26,500 (as of October 2026), or stretching toward a 2026 Volkswagen Atlas, starting at $39,310 (as of October 2026) or the 2026 Volkswagen ID.4, starting at $45,095 (as of October 2026), often benefit most from bringing a strong co-signer — because the credit tier assigned at underwriting drives the rate, and the rate drives the payment. The sales department is open Monday through Saturday from 9:00 am to 7:00 pm, which is useful for coordinating a co-signer who works weekdays.
"Amazing people, great advice from the finance team. Jackson, David and Matt were great to work with.!" — 5★ · Paul, Sep 2026
Frequently asked questions
Can I get a VW loan with a co-signer in Utah if my credit score is below 580?
Possibly, but it is not guaranteed. Scores in the lower ranges are generally viewed as poor, and Volkswagen Credit does not publish a universal minimum credit score. A co-signer with strong credit and sufficient income improves your odds and may improve your rate, but the lender evaluates the full application — your income, your debts, the vehicle, and the down payment — not just the co-signer's score.
Does my co-signer need to live in Utah?
No, but both applicants must be physically present to complete a joint finance application — either at the dealership in Salt Lake City or online. An out-of-state co-signer should plan the online option in advance and have their SSN or ITIN, valid ID, proof of income, proof of residence, and employment details ready. Missing documents stop the deal.
Can a co-signer be removed from a VW auto loan later?
Not directly on the original loan. Co-signers are typically released only when the loan is refinanced in the primary borrower's name alone or paid off entirely. Many Salt Lake Valley buyers plan for this: use a co-signer to secure the initial financing, build a record of on-time payment history, then refinance once your own credit supports approval.
Will co-signing hurt my ability to get my own loan?
It can. When you co-sign for a loan, it is included in your credit history and incorporated into your debt-to-income ratio. That means lenders evaluating you for a mortgage, personal loan, or your own auto loan will count the co-signed Volkswagen debt against your borrowing capacity, even though you're not the one driving the car.
What happens to the co-signer if the primary borrower misses a payment?
Both credit scores take the hit. A single missed payment can damage both the primary borrower's and the co-signer's credit score, and the co-signer can be held responsible for the debt, late fees, and collection costs under CFPB guidance. Co-signers should ask for payment-status alerts from the lender so they know immediately if something slips.
Can I use a co-signer to qualify for a low-down-payment VW purchase?
Yes, that's one of the common use cases. A strong co-signer can help a buyer with limited credit history qualify for financing terms that include a lower down payment, because the lender's reduced risk opens up more flexible loan structures. The specific down-payment requirement still depends on the vehicle, your credit, and the lender's underwriting on the day of application.
The bottom line for Salt Lake Valley buyers
A co-signer is a legitimate, powerful tool for first-time or thin-file Volkswagen buyers — but it is not a shortcut, not a guarantee, and not consequence-free for the person signing. Treat it as what it actually is: a second credit profile the lender uses to price risk, backed by a second person who is fully on the hook.
Readers in the Salt Lake Valley who want to walk through a co-signed Volkswagen application with someone who handles them every week can reach Strong Volkswagen at (801) 285-9033 or https://www.strongvw.com to get the documentation list, confirm both parties can attend, and start the pre-qualification conversation.