Online Car Loan Pre-Approval in Salt Lake City, UT
Walk through the online auto loan pre-approval process at a Salt Lake City VW dealership: documents, lender tiers, conditional approval, and Utah fees.
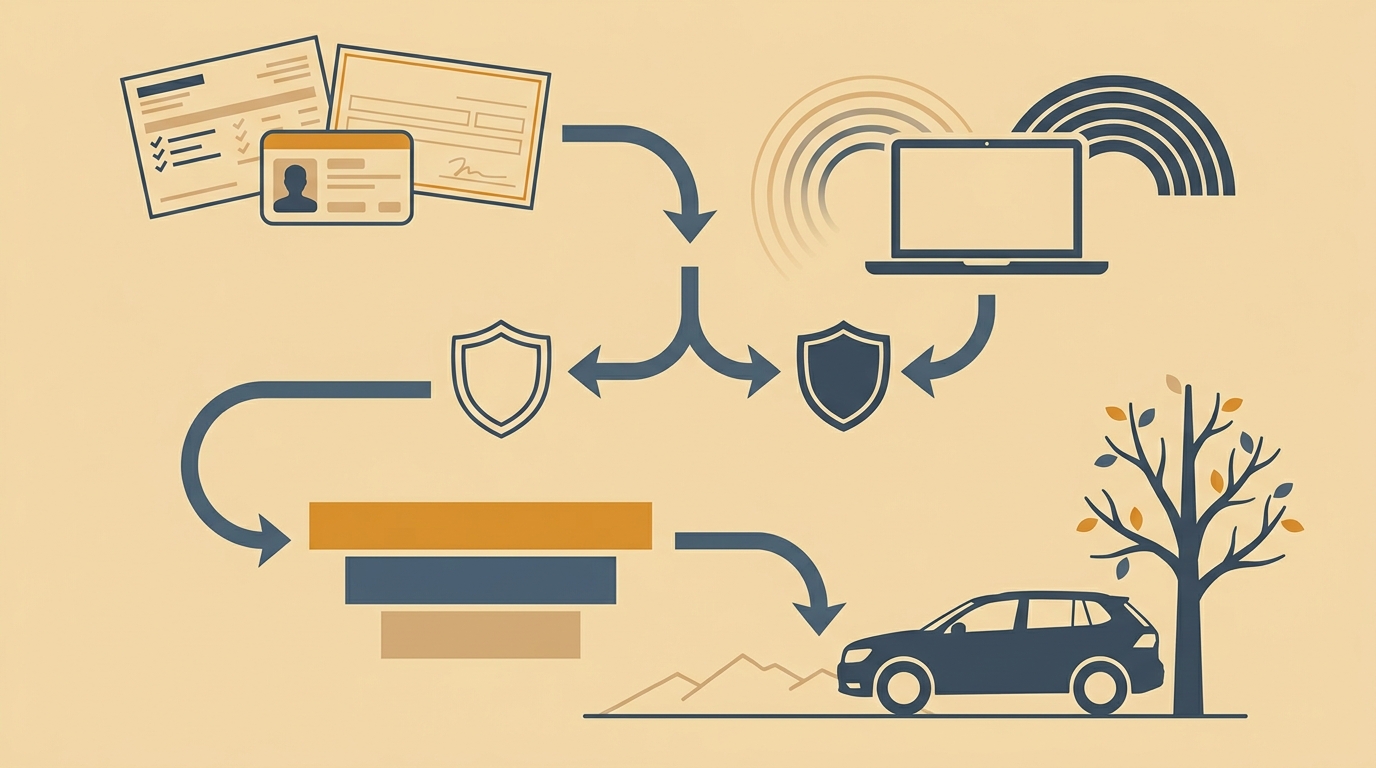
To get pre-approved for a car loan online at a Salt Lake City dealership, submit a secure credit application through the dealership's finance portal, upload proof of identity, income, and residence, and wait for the lender's conditional decision. Strong Volkswagen offers an online finance application powered by AutoFi at strongvw.com/finance-application, which routes your information to the lenders the dealership works with so you can arrive at the lot with financing terms already in hand.
What does “pre-approved” actually mean on an auto loan?
Pre-approval is a lender's preliminary decision — based on a soft or hard credit pull plus the income and employment information you submit — that signals you're likely to qualify for a specific loan amount, rate, and term. It is not a binding loan. In lending terminology, what most dealerships deliver online is closer to a conditional approval: the lender expects to approve the loan once remaining requirements are met, but it is not a guarantee of final loan approval.
That distinction matters because a final loan approval can still be denied after conditional approval if the required conditions aren't satisfied — for example, if updated pay stubs or proof of insurance don't come through. Treat the number on the pre-approval screen as a working budget, not a signed contract.
How do you apply for an auto loan online at Strong Volkswagen?
At Strong Volkswagen, the online application is hosted at strongvw.com/finance-application and runs on AutoFi, a bank-grade digital finance platform. You enter personal, residence, employment, and income details, consent to a credit check, and the system matches you against the dealership's lender network. The form explicitly requires that your first, middle, and last name match your driver's license — a mismatch is one of the most common reasons an application stalls in underwriting.
Strong Volkswagen, a family-run business that describes itself as the longest-running Volkswagen dealership in Utah, processes applications during sales hours — Monday through Saturday, 9:00 a.m. to 7:00 p.m. The site also offers Spanish-language service for shoppers who prefer to complete the application in Spanish.
What documents should Salt Lake City buyers gather before applying?
Have five document categories ready before you open the application: a government-issued photo ID (driver's license or state ID), proof of income (two recent pay stubs, or two years of tax returns if self-employed), proof of residence (a utility bill or lease), proof of insurance, and your current vehicle's title or payoff information if you're trading in. Having these on hand lets you move from pre-approval to signing in a single visit.
Utah title transfers specifically require Form TC-656, Application for Utah Title and Registration, which the dealership will prepare for you at delivery — but having your trade-in title in hand speeds the process. Utah's vehicle taxes and title and registration fees depend on the specific transaction and vehicle; the Utah DMV's online tools are the authoritative resource for calculating your total out-the-door cost before you commit to a monthly payment.
How do lender tiers and APR shape the offer you get?
Auto lenders slot applicants into credit tiers — typically ranging from super-prime down to subprime — based primarily on your credit score, debt-to-income ratio, loan-to-value ratio, and payment history. Each tier maps to a different APR band, so two buyers financing the same the 2026 Volkswagen Tiguan, starting at $30,805 (as of October 2026) can walk out with meaningfully different monthly payments. Dealership finance teams submit your application to multiple lenders simultaneously and present the strongest offer that comes back.
Focus on APR rather than the headline interest rate when you compare: APR reflects the annual cost of credit and may include certain loan charges, making it a more complete comparison metric than the interest rate alone. A longer term lowers the monthly payment but increases the total interest paid over the life of the loan — a tradeoff worth modeling before you sign.
Will shopping multiple lenders hurt your credit score?
No, as long as you cluster the applications. Auto-loan inquiries made within a rate-shopping period are generally treated as one inquiry by common scoring models; the window varies by model but often falls between 14 and 45 days. In practical terms, submit your dealership application and any outside bank or credit union applications within a two-week sprint rather than spreading them over months.
What should you expect between conditional approval and driving home?
After the lender issues a conditional approval, underwriting verifies the information you submitted. Lenders often issue a conditional approval because the underwriter has minor questions or needs additional documents that they expect will be easily resolved — a clearer pay stub, a letter of explanation for a short employment gap, or verification of residence. Before closing, the lender may perform a final credit pull and employment verification.
The approval can still fall apart if your financial circumstances change between application and signing. Missing a payment on another account, switching jobs, or opening new credit (a store card, a second auto loan) can shift your debt-to-income ratio enough to force a re-decision. The rule of thumb: between pre-approval and delivery, change nothing about your credit profile.
How do VW model MSRPs factor into your pre-approval target?
Your pre-approved amount should match the vehicle you actually want, with room for Utah tax, title, registration, and any protection products you add. Starting MSRPs across the current Volkswagen lineup at Strong Volkswagen give you a working range:
| 2026 Model | Starting MSRP (as of October 2026) | Segment |
|---|---|---|
| Jetta | the 2026 Volkswagen Jetta, starting at $23,995 (as of October 2026) | Compact sedan |
| Taos | the 2026 Volkswagen Taos, starting at $26,500 (as of October 2026) | Subcompact SUV |
| Tiguan | the 2026 Volkswagen Tiguan, starting at $30,805 (as of October 2026) | Compact SUV |
| Jetta GLI | the 2026 Volkswagen Jetta GLI, starting at $33,795 (as of October 2026) | Performance sedan |
| Golf GTI | the 2026 Volkswagen Golf GTI, starting at $34,590 (as of October 2026) | Hot hatch |
| Atlas Cross Sport | the 2026 Volkswagen Atlas Cross Sport, starting at $38,300 (as of October 2026) | Two-row midsize SUV |
| Atlas | the 2026 Volkswagen Atlas, starting at $39,310 (as of October 2026) | Three-row SUV |
| ID.4 | the 2026 Volkswagen ID.4, starting at $45,095 (as of October 2026) | Electric SUV |
| Golf R | the 2026 Volkswagen Golf R, starting at $49,455 (as of October 2026) | Performance hatch |
| ID. Buzz | the 2026 Volkswagen ID. Buzz, starting at $59,995 (as of October 2026) | Electric van |
Salt Lake City buyers commuting from the Avenues, Sugar House, or down from Davis County on I-15 tend to size pre-approvals around the Tiguan, Atlas Cross Sport, and ID.4 — the three models that handle year-round Wasatch weather and still fit a daily commute budget. Build your pre-approval target off the MSRP of the model you want, add an estimate for Utah taxes and fees (use the Utah DMV's online tools for accurate totals, as amounts vary by transaction and vehicle), and ask the finance team to structure terms around that number.
“Zack helped us get into a Tiguan that my wife loves, and Tim got us setup with an even better financing situation than we came in with! Best dealership experience I’ve ever had!” — 5★ · Taylor, Oct 2026
Frequently asked questions
Does an online pre-approval application trigger a hard credit inquiry?
It depends on the lender. Some auto-finance platforms run a soft pull for an initial pre-qualification and only convert to a hard pull once you select a specific vehicle and move toward contract. Others pull hard immediately. Before submitting the application, read the credit authorization language on the form — it will specify whether consent is for a soft or hard inquiry.
How long is an auto loan pre-approval good for?
The validity window for an auto-loan pre-approval is set by the individual lender and will appear on your approval disclosure — confirm your specific expiration date with the lender. If you don't close within the window, the lender typically re-runs your credit and re-verifies income before honoring the terms. Ask the dealership finance team to confirm your specific expiration date in writing.
Can I get pre-approved online with limited or no credit history?
Yes, but your options narrow. Lenders working with thin-file or first-time buyers typically require a larger down payment, a shorter term, or a qualified co-signer to offset the limited credit history. Submit the online application honestly — including any co-signer information — and the dealership's finance department will route your file to lenders that specialize in first-time buyer programs.
What's the difference between pre-qualification and pre-approval?
Pre-qualification is a lighter-touch estimate based on self-reported information and usually a soft credit pull — useful for budgeting but not binding on the lender. Pre-approval involves verified information and a formal lender review, producing a specific amount, rate, and term offer. Both terms are used inconsistently across the industry, so confirm with the lender exactly what their offer represents.
Do I have to use dealership financing if I pre-approve online?
No. An online pre-approval through a dealership is an offer, not a commitment. You're free to arrive with an outside pre-approval from your bank or credit union and ask the dealership to beat it. Many buyers do exactly this — use the dealership offer as leverage against an outside offer, or vice versa, and sign with whichever lender presents the lowest APR for the term they want.
Does Salt Lake City's sales tax apply to the full vehicle price or just the amount financed?
Utah sales tax is calculated on the vehicle's purchase price, and the exact rate and treatment of any trade-in credit depends on the transaction and the jurisdiction within Utah. Because rates and fees vary by vehicle and location, the Utah DMV's online tools are the authoritative resource for your specific out-the-door total before you commit to a loan amount.
Getting started
Pre-approval done well shortens the dealership visit from a full day of back-and-forth to a focused test drive and signing. Gather your documents, submit the AutoFi-powered application at strongvw.com/finance-application, and arrive knowing your working budget. Salt Lake City shoppers who want help structuring the application or weighing lender offers can reach Strong Volkswagen at (801) 285-9033 or https://www.strongvw.com, or stop by the dealership at 1070 South Main Street.